Payment Decoded - What is an Acquirer and Why They Are Essential?
Every time a merchant accepts a card payment; a powerful engine works in the background to make it happen: the Acquirer. While shoppers often interact with the card reader or online checkout, it’s the Acquirer that enables the merchant to accept that payment in the first place.
From global retailers to independent boutiques, every business that takes card payments relies on an Acquirer to connect with the payment ecosystem, reduce fraud, and ensure funds arrive in their account.
What is an Acquirer?
The Acquirer, or acquiring bank, is the financial institution or payment processor that works on behalf of the merchant. Its job is to:
- Provide the infrastructure to accept card payments
- Receive payment requests from the merchant
- Communicate with the card network or schemes (Visa, Mastercard, etc.)
- Forward the transaction to the cardholder’s Issuer for approval
- Settle the funds into the merchant’s account once the payment is approved
Acquirers also offer fraud screening, reporting tools, and chargeback management, helping merchants operate securely and efficiently.
Where Acquirers Fit in the Payment Ecosystem
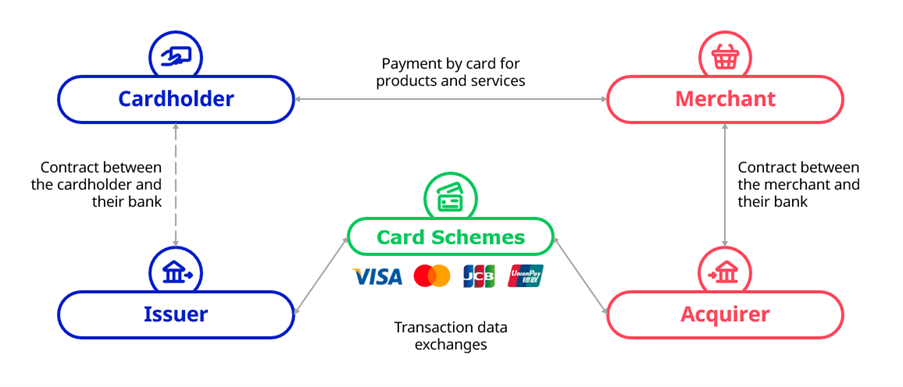
Each card payment involves four key participants, commonly referred as the "four corners" of the payments system:
- Cardholder: The customer making the purchase.
- Issuer: The cardholder’s bank, which approves or denies the transaction.
- Acquirer: The merchant’s bank or payment processor.
- Merchant: The business accepting the payment.
Here’s how it works, all in just a few seconds:
- The cardholder inserts or taps their card.
- The transaction request is sent to the Acquirer.
- The Acquirer routes it through the card network (like Visa or Mastercard).
- The Issuer checks the request and sends back an approval or decline.
- If approved, the response travels back through the chain to the merchant, and the sale is completed.

Why Acquirers Matter for Shoppers
Shoppers may never hear about the Acquirer, but it plays a critical role in every card payment they make. Without the Acquirer, there’s no connection between the merchant and the rest of the payment ecosystem. Acquirers ensure that:
-
Transactions are seamless: They allow fast real-time authorization and settlement, so customers experience smooth and efficient checkouts.
-
Cards work anywhere: By partnering with global card networks and payment platforms, Acquirers help merchants accept a broad range of cards and digital wallets.
-
Security is built in: Acquirers invest in risk engines and fraud detection systems that silently protect the shopper from suspicious or unauthorized use.

Why Acquirers Matter for Merchants
For merchants, the Acquirer is not just a service provider: it's a payment partner. Every transaction, from card acceptance to fund settlement, depends on the Acquirer's infrastructure, expertise, and support. Acquirers help merchants:
- Get paid, reliably: They handle the technical and financial side of card acceptance, from connecting with the card network to receiving funds.
- Protect their revenue: With tools for fraud screening and chargeback mitigation, Acquirers reduce the risk of financial loss.
- Understand performance: Dashboards, transaction logs, and analytics help merchants monitor and improve their operations.
- Scale easily: Whether expanding internationally or adding new payment types, merchants can rely on their Acquirer to grow with them.
The Acquirer is the backbone of card payment acceptance. It empowers merchants to take payments from anyone and anywhere, securely, efficiently, reliably.
FAQ — Things to Know About Acquirers
Yes — without one, they cannot connect to card networks.
Not always. The terminal may be provided by a third party, but it connects to the Acquirer for transaction processing.
Yes. Most Acquirers support credit cards, debit cards, wallets, and even local payment methods.
Both play a role, but the Acquirer assists the merchant in managing chargebacks.
Get in touch
Let's connect and discover the ideal way that we can support your needs.


